Market Insights·15 June 2025·3 min read·Alexander Guselnikov
Geopolitics Trump Inflation - week ending 15/06/2025
Markets came under pressure this week, as geopolitical tensions in the Middle East collided with another round of inflation data, denting the calm that had prevailed since mid-May.
Markets Performance
Markets came under pressure this week, as geopolitical tensions in the Middle East collided with another round of inflation data, denting the calm that had prevailed since mid-May. While softer CPI and PPI prints gave fleeting hope to rate-cut bulls, a sudden escalation in the Israel–Iran conflict and hotter-than-expected consumer sentiment figures spiked volatility and triggered a reversal in equities into week’s end. Traders were left juggling the familiar trifecta: disinflation, geopolitics, and central bank ambiguity. Breadth deteriorated, small caps lagged sharply, and the VIX surged back above 20 for the first time in nearly two months.
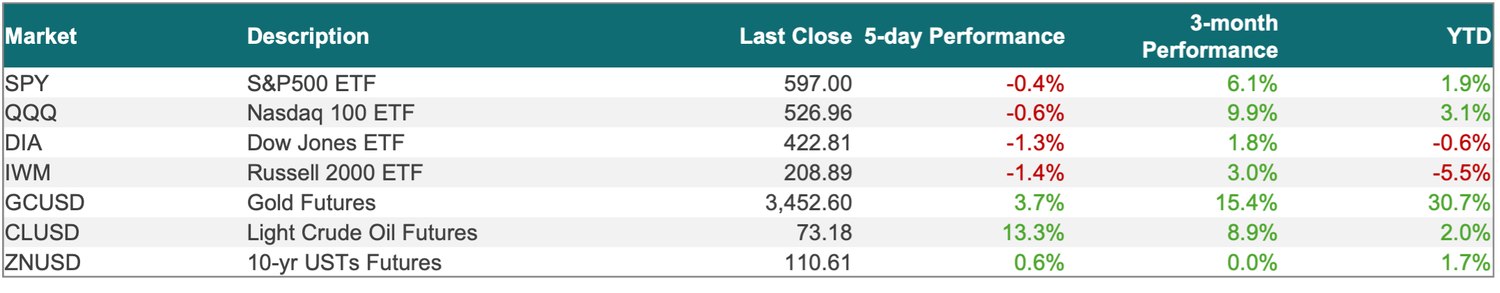
The S&P 500 (SPY) slipped –0.4% to close at 597.00, while the Nasdaq 100 (QQQ) lost –0.6%, dragged by mega-cap digestion and mild profit-taking in AI-linked names. The Dow (DIA) dropped –1.3%, and the Russell 2000 (IWM) was hit hardest, falling –1.4% as cyclical risk appetite quickly evaporated. Small caps now sit –5.5% YTD, a stark contrast to the 30% rally in gold (GCUSD), which rose another +3.7% this week to $3,452.60 amid safe-haven flows and surging energy prices. Crude oil (CLUSD) surged +13.3% to $73.18 — its best weekly gain in 2025 — on refinery strike threats, OPEC jawboning, and fears of Iranian disruption in the Persian Gulf. Meanwhile, 10-year U.S. Treasury futures (ZNUSD) rose +0.6% as yields briefly dipped post-CPI before reversing higher into Friday’s risk-off close.
The macro landscape turned sharply on Wednesday. Headline CPI rose just +0.1% MoM (vs. 0.2% expected), while Core CPI slowed to +0.1% MoM and +2.8% YoY — confirming a continuation of the disinflation trend. PPI, too, came in light across both headline and core prints, but the calm was short-lived. Thursday brought hotter-than-expected initial jobless claims (248K vs. 240K consensus), and Friday’s University of Michigan Consumer Sentiment surged to 60.5 (vs. 53.5 expected) — the largest beat since early 2023. More notably, 1-year inflation expectations remained stubbornly elevated at 5.1%, muddying the policy path ahead.
However, the dominant catalyst was geopolitical. On Thursday, headlines emerged that Israel had conducted a retaliatory strike on Iran’s ballistic missile infrastructure, following direct Iranian attacks on civilian and strategic targets including near the Dimona nuclear facility. Markets responded swiftly: the VIX jumped +16.3% on Friday alone, while oil and gold exploded higher. The 10-year Treasury yield snapped higher by week’s end to 4.42%, while the front end of the curve priced out ~15bps of rate cut expectations as stagflation fears bubbled beneath the surface. The VIX 1-month to 3-month ratio signalled a buy at Friday open, and markets did rally until early afternoon when continued strikes in the Middle East and uncertainty came back to close the week near the lows.
In short, this week marked a repricing of tranquillity. After weeks of low realized volatility and steadily climbing indices, the reemergence of geopolitical risk added a sharp edge to macro positioning. With the FOMC decision, retail sales, and global trade negotiations on deck for next week, investors may be entering a period where macro catalysts dominate once again — and where good news may no longer be good enough.
To read the full version of this week’s insights please click the “view in PDF” button at the top.
This investment thesis is prepared by Altai Capital for informational and analytical purposes. Investors should conduct independent due diligence and consult with financial advisors before making investment decisions. Past performance and historical precedents do not guarantee future results. Altai Capital’s portfolio may contain the mentioned security and thus this publication have vested interests.
This note is published for informational purposes only and is not investment advice or a recommendation to buy or sell any security. The author may hold positions in securities discussed. See the full disclaimer in the footer.
Keep reading
 Research Summit
11 October 2025 · 2 min read
$NTGR, Netgear Inc. - Likely Regulatory Tailwinds
Netgear represents a compelling opportunity to capitalize on potential U.S. regulatory action against Chinese router manufacturer TP-Link, which commands 65% of the U.S. market.
Read more Markets
7 September 2025 · 7 min read
Labour Markets Slowly Deteriorate as Inflation Buoys - week ending 07/09/2025
Equities digested a mixed macro tape but finished the week with a mild risk-on tone at the index level. SPY eked out +0.3%, while QQQ and IWM outperformed (+1.0% and +1.1%), with DIA slipping −0.2%.
Read more Markets
6 July 2025 · 8 min read
Markets at Extremes as we Enter Trade News Week - week ending 06/07/2025
U.S. equity markets extended their bullish streak through the shortened holiday week, with strong breadth and firm price action across all major indices.
Read more