Market Insights·7 September 2025·7 min read·Alexander Guselnikov
Labour Markets Slowly Deteriorate as Inflation Buoys - week ending 07/09/2025
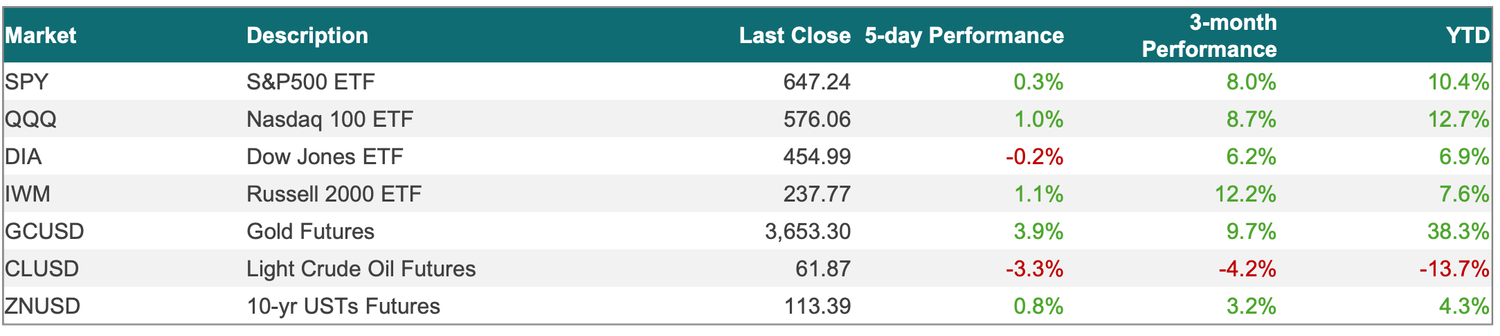
Equities digested a mixed macro tape but finished the week with a mild risk-on tone at the index level. SPY eked out +0.3%, while QQQ and IWM outperformed (+1.0% and +1.1%), with DIA slipping −0.2%.
Markets Performance
Equities digested a mixed macro tape but finished the week with a mild risk-on tone at the index level. SPY eked out +0.3%, while QQQ and IWM outperformed (+1.0% and +1.1%), with DIA slipping −0.2%. Factor leadership re-centered on mega-cap tech, communication services and AI infrastructure led early, while small caps found a bid into Friday despite softer jobs data. Commodities and rates reflected a growth-scare tilt: gold broke higher and carried strong follow-through after August’s advance as Western ETF demand accelerated, crude rolled over, and duration firmed as yields slipped.
Labor data landed soft and kept the “policy easing ahead” narrative intact. Nonfarm payrolls rose +22k, unemployment held at 4.3%, and average hourly earnings printed +0.3% m/m (+3.7% y/y), alongside modest net negative revisions - cooling employment without a wage flare. That combination pressed the front end lower, nudged the dollar down, and helped extend bullion’s breakout as a portfolio hedge. Equities faded into Friday’s close on cyclical sensitivity, but the weekly tone stayed constructive with dispersion beneath the surface.
Flows and breadth improved through mid-week as investors rotated out of crowded leaders into under-owned cyclicals. A brief momentum shakeout in extended growth and AI made room for industrials, financials, and parts of healthcare to catch a bid, with up-volume broadening and new highs extending beyond the usual AI complex. Options dynamics remained supportive, low implied vol and steady dealer long-gamma kept intraday swings contained - reinforcing the “buy-the-dip, fade-the-chase” regime from this summer.
Energy and geopolitics added nuance. Headlines around OPEC’s August output increase (roughly +400 kb/d) and ongoing Middle East tensions were outweighed by demand worries; crude rolled over into the weekend despite a firm start. Auto/EV news flow stayed busy with Tesla recording its best wholesale month in China this year while semis were mixed and select software underperformed on valuation sensitivity. With a modest dollar slippage and softer yields, defensives and gold outperformed, while value pockets rallied on rotation rather than beta.
Gold’s advance accelerated into week-end, settling near $3,653/oz and breaking out of recent ranges as real yields eased and US investors increasingly “grabbed the baton” from EM buyers. Western ETF inflows picked up late in August and momentum carried into early September. In this backdrop, front-end rates anchored by rate cut odds and the long end sticky on term premium - bullion’s sensitivity to US real rates remains the swing factor; dips continue to attract allocation
Earnings skewed toward AI plumbing and consumer read-throughs. AVGO posted a strong print and ranked among the week’s top S&P movers, underscoring ongoing demand for AI infrastructure. CRDO and IOT added incremental signals around networking and AI-adjacent software demand. In small caps, AEO was a standout with a sharp post-print rebound, consistent with a tentative broadening beyond megacap growth. We also tracked optical and interconnect suppliers for confirmation that AI data-center capex remains resilient into year-end.
Looking ahead, the setup tightens into the CPI/PPI cluster, claims, sentiment, and central-bank speak. The path of least resistance remains higher so long as laborcools without an inflation re-acceleration; however, the market’s reliance on a narrow set of growth leaders keeps drawdown asymmetry in play, making rotation discipline and macro-aware hedging critical into the data.
Macro Data this Week
Key Data - Wednesday 3rd September
JOLTS openings eased to 7.181M (vs 7.4M est.), consistent with a gradual cooling in labor demand. Factory Orders came in at -1.3% (vs -1.4%) suggest soft—but stabilizing—goods momentum, while mortgage applications remained rate-constrained (composite −1.2%, purchase −3.1%, refi +0.9%).
The Beige Book arrived ahead of Thursday’s heavier slate (ADP, claims, productivity, PMI Composite, ISM Services, EIA), giving timely colour on hiring, wages, and pricing across districts.
Fed communication set expectations for gradualism, Kashkari noted breakeven jobs near ~75k/month, Waller kept the door open to a cut as soon as the next meeting (and potentially multiple), while Bostic and Musalem emphasized cooling labor amid still-elevated—but moderating—price pressures.
Key Data - Thursday 4th September
Labor indicators stayed soft with Challenger job cuts 85,979 (highest Aug since 2020), ADP +54k (vs 65k), and initial claims 237k (vs 230k), reinforcing a slower hiring pace even as overall conditions remain orderly.
ISM Services 52 (vs 51) and PMI Composite 54.6 / Services 54.5 signal slow expansion, while the trade deficit widened to −$78.3B, trimming the net-export contribution to growth.
Productivity provided a cushion with Nonfarm Productivity +3.3% (vs 2.7%) and Unit Labor Costs +1.0% (vs 1.2%); energy data showed an EIA crude build +2.41M and NatGas +55bcf, while GDPNow held at 3.0% for Q3-2025 on solid consumption (2.1%) and investment (6.0%), partly offset by softer net exports (0.28pp).
Key Data - Friday 5th September
The employment report pointed to slower labor demand without a wage flare: NFP +22k (vs +75k), unemployment 4.3%, AHE +0.3% m/m; +3.7% y/y, and net revisions of −21k with the Fed in blackout into next week’s inflation data.
Participation 62.3% and employment-population 59.6% were steady; long-term unemployed stood at 1.9M. Industry gains were led by health care (+31k) and social assistance (+16k), offset by declines in federal government (−15k), manufacturing (−12k; −15k in transportation equipment, strike-related), and wholesale trade (−12k).
Hours and pay were steady, the workweek held at 34.2 hours, and nonsupervisory earnings rose +0.4% m/m, reinforcing the picture of a cooling but orderly labor market heading into CPI/PPI.
Themes in Play
Gold - Jackson Hole Breakout
Gold settled at $3,653.3/oz on Friday, extending a powerful post–Jackson Hole advance; momentum reflects a classic stagflation-hedge bid with strong year-to-date gains.
The driver mix has shifted toward Western ETF demand as real yields eased and the curve bull-steepened; with the front end anchored by cut expectations and the long end sticky on term premium, gold’s sensitivity to US real rates remains the key swing factor.
Participation is broadening beyond central-bank buying as tactical funds add on breakouts and dips remain shallow; positioning still isn’t stretched enough to cap upside unless real yields lurch higher.
Into next week’s inflation prints, a benign CPI/PPI sequence would reinforce the bid, while any long-end selloff likely produces only a consolidation given robust demand from macro hedgers and systematic trend models.
Rate Cuts in the Face of Worsening Employment and Inflation
The latest labor cluster softened again: payrolls rose +22k, the unemployment rate ticked up to 4.3%, and prior months saw net revisions of −21k. Wages held at +0.3% m/m (+3.7% y/y). Fed-speak leaned cautiously dovish into the data. Chicago’s Goolsbee flagged that job growth below breakeven and rising layoff risk would be concerning and noted shocks pushing toward stagflation - the mix that keeps the easing door open even as the inflation fight isn’t fully won. BlackRock’s Rosenberg added that the Fed is “likely back in motion for cuts,” matching futures that priced more easing post-print.
Historically, there are few clean precedents where the Fed cut with rising unemployment, above-target inflation, and equity benchmarks near highs simultaneously; most modern easing cycles paired elevated inflation with weak equities (1970s) or strong equities with benign inflation (2019). The absence of a neat analog argues for wider outcome bands and more respect for path dependency through the CPI/PPI sequence.
Rates market behavior - gentle bull-steepening with the front end anchored by cuts, long end sticky on term premium - fits a “growth-down > inflation-up” regime also evident in gold’s resilience as stagflation hedging picks up among Western ETF buyers.
LLM Training - Reddit Stands out
Reddit’s intent-rich, moderated communities provide a high-signal corpus that is uniquely attractive for AI training, creating a second monetization leg via data licensing alongside a faster, more measurable direct-response ads engine.
In June 2025, Reddit was the most popular domain for large language models to cite, almost doubling Wikipedia’s traffic which placed second.
Engagement depth and commercial outcomes are trending in the right direction: a large daily active user base, rapid revenue growth, positive free cash flow, and minimal capex together point to operating leverage as scale improves.
Balance-sheet flexibility (net cash, low capital intensity) allows continued investment in safety, tooling, and partnerships without stressing liquidity; that optionality is valuable in a volatile ad cycle.
In the latest earnings call in August, Reddit guided to a 55% year-on-year revenue growth for 2026 and a 105% EBITDA increase year-on-year.
Lithium & EVs Show Signs of Life
After a deep multi-year drawdown, signs of stabilization are emerging across the chain. ALB has turned up through key moving averages, with improving price action aligning to an early basing dynamic in lithium markets—an inflection that sets up operating leverage if prices continue to firm.
Supply is quietly tightening at the margin. Sector commentary highlights “less global production” as high-cost projects slow or pause; market chatter around a temporary shutdown at a major Chinese converter underscores this trend. Even a low-single-digit share of global LCE capacity going offline can swing short-term balances given thin inventories and high demand elasticity.
Demand markers are incrementally better. TSLA just logged its best wholesale month in China this year, while mix shifts toward more affordable models and energy storage help smooth the demand curve beyond pure passenger EV cycles.
Setup and risks: the near-term path is sensitive to China production cadence and promotional cycles; a renewed price downdraft remains the primary risk, but positioning and emerging supply discipline keep risk-reward improving for quality names.
To read the full version of this week’s insights please click the “view in PDF” button at the top.
This investment thesis is prepared by Altai Capital for informational and analytical purposes. Investors should conduct independent due diligence and consult with financial advisors before making investment decisions. Past performance and historical precedents do not guarantee future results. Altai Capital’s portfolio may contain the mentioned security and thus this publication have vested interests.
This note is published for informational purposes only and is not investment advice or a recommendation to buy or sell any security. The author may hold positions in securities discussed. See the full disclaimer in the footer.
Keep reading
 Research Summit
11 October 2025 · 2 min read
$NTGR, Netgear Inc. - Likely Regulatory Tailwinds
Netgear represents a compelling opportunity to capitalize on potential U.S. regulatory action against Chinese router manufacturer TP-Link, which commands 65% of the U.S. market.
Read more Markets
6 July 2025 · 8 min read
Markets at Extremes as we Enter Trade News Week - week ending 06/07/2025
U.S. equity markets extended their bullish streak through the shortened holiday week, with strong breadth and firm price action across all major indices.
Read more Markets
29 June 2025 · 2 min read
Markets Hit All Time Highs, Again - week ending 29/06/2025
Equity markets posted strong, broad-based gains this week, in spite of hotter-than-expected macroeconomic prints and dovish signals from Federal Reserve officials.
Read more