Market Insights·29 June 2025·2 min read·Alexander Guselnikov
Markets Hit All Time Highs, Again - week ending 29/06/2025
Equity markets posted strong, broad-based gains this week, in spite of hotter-than-expected macroeconomic prints and dovish signals from Federal Reserve officials.
Equity markets posted strong, broad-based gains this week, in spite of hotter-than-expected macroeconomic prints and dovish signals from Federal Reserve officials. The S&P 500 (SPY) rose 3.5%, its best weekly gain since April, while the Nasdaq 100 (QQQ) advanced 4.0% amid renewed strength in megacap tech names. The Dow Jones (DIA) gained 3.9%, driven by a strong showing in financials and industrials. Small caps (IWM), which have lagged most of the year, delivered a 3.0% weekly return as investors tentatively rotated into more cyclical exposures.
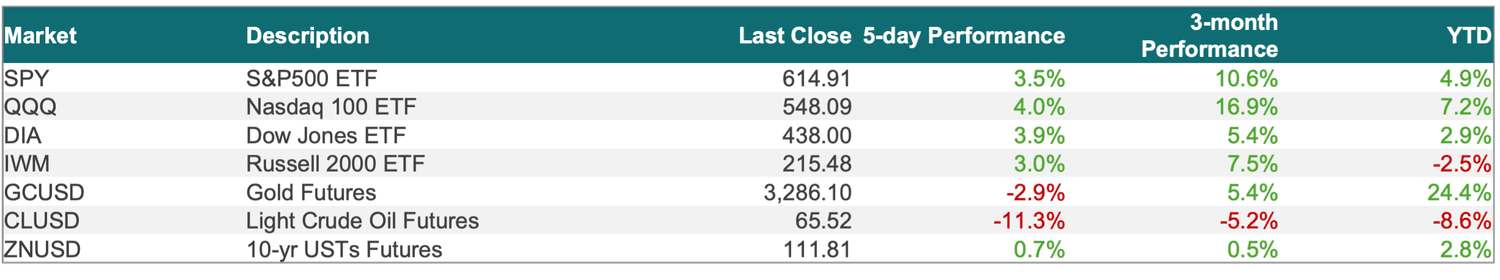
Beneath the surface, investors digested a combination of subdued housing prints and Fed speak that reinforced a "higher-for-longer" narrative while keeping the door open to potential easing later in the year. Crude oil experienced significant volatility, tumbling 11.3% on the week following a surprise -5.8 million barrel inventory draw that was offset by surging domestic production and signs of softer end demand. NatGas volatility surged midweek, adding to energy sector weakness. Meanwhile, gold (GCUSD) slid -2.9% as real rates edged higher, while the 10-year U.S. Treasury yield inched up just 0.7%, finishing at 111.81.
Investor positioning remains cautious, particularly in cyclicals and value sectors, though market breadth showed notable improvement late in the week. Flows into broad equity ETFs picked up midweek, but thematic and sector-specific funds still show muted conviction. Key macro events included disappointing New Home Sales and MBA mortgage applications, both pointing to housing affordability constraints. A mild risk-off tone emerged midweek on geopolitical concerns—particularly headlines out of the Middle East and continued shipping disruption fears - but was ultimately overshadowed by dovish Fed commentary from numerous speakers. The VIX closed down 4.35% at 16.72, near multi-month lows, suggesting rising confidence in the near-term equity narrative.
Additionally, the options market showed signs of growing bullishness, with put/call ratios falling and SKEW rising into the end of the week—a sign of more interest in upside tail risk hedging. Margin debt continues to rise, albeit at a slower pace than prior quarters, and retail flows into single stocks saw their largest weekly increase since January. Notably, discretionary sectors led the gains, while defensives underperformed, pointing to a slight risk-on tilt by institutional allocators. Contrary to this, post earnings momentum has faded recently albeit on a smaller sample size as earnings are in hibernation.
In commodities, the steep drop in crude was partly driven by positioning washouts and algorithmic momentum unwinds, particularly in the back half of the week. The OPEC+ calendar remains in focus for July, with several Gulf producers hinting at potential supply recalibrations if Brent stays below $80. On the FX side, the USD traded flat on the week, but emerging market FX showed strength, with BRL and MXN leading on the back of positive trade data. Meanwhile, global equity correlations declined, suggesting a renewed dispersion environment that favors stock-picking and cross-market arbitrage strategies.
To read the full version of this week’s insights please click the “view in PDF” button at the top.
This investment thesis is prepared by Altai Capital for informational and analytical purposes. Investors should conduct independent due diligence and consult with financial advisors before making investment decisions. Past performance and historical precedents do not guarantee future results. Altai Capital’s portfolio may contain the mentioned security and thus this publication have vested interests.
This note is published for informational purposes only and is not investment advice or a recommendation to buy or sell any security. The author may hold positions in securities discussed. See the full disclaimer in the footer.
Keep reading
 Research Summit
11 October 2025 · 2 min read
$NTGR, Netgear Inc. - Likely Regulatory Tailwinds
Netgear represents a compelling opportunity to capitalize on potential U.S. regulatory action against Chinese router manufacturer TP-Link, which commands 65% of the U.S. market.
Read more Markets
7 September 2025 · 7 min read
Labour Markets Slowly Deteriorate as Inflation Buoys - week ending 07/09/2025
Equities digested a mixed macro tape but finished the week with a mild risk-on tone at the index level. SPY eked out +0.3%, while QQQ and IWM outperformed (+1.0% and +1.1%), with DIA slipping −0.2%.
Read more Markets
6 July 2025 · 8 min read
Markets at Extremes as we Enter Trade News Week - week ending 06/07/2025
U.S. equity markets extended their bullish streak through the shortened holiday week, with strong breadth and firm price action across all major indices.
Read more