Market Insights·22 June 2025·3 min read·Alexander Guselnikov
Market Pricing Stagflation as Tensions Escalate - week ending 22/06/2025
Markets retrenched over the past week, reversing a multi-week stretch of relative strength as a mix of soft macro data, hawkish central bank signalling, and rising geopolitical tensions weighed on sentiment.
Markets Performance
Markets retrenched over the past week, reversing a multi-week stretch of relative strength as a mix of soft macro data, hawkish central bank signalling, and rising geopolitical tensions weighed on sentiment. Investors appeared to take profits across key risk assets amid an increasingly fragile backdrop. The S&P 500 (SPY) declined –1.6%, with losses led by industrials and discretionary sectors, while the Nasdaq 100 (QQQ) slid –1.3% as AI-linked mega caps paused their advance. The Dow (DIA) lagged the most, falling –2.0%, reflecting cyclical underperformance and weakness in rate-sensitive constituents. Meanwhile, Small caps (IWM) extended their year-to-date slide with a –1.7% weekly loss, leaving the index –5.3% YTD, highlighting continued aversion to high-beta exposures amid narrowing breadth.
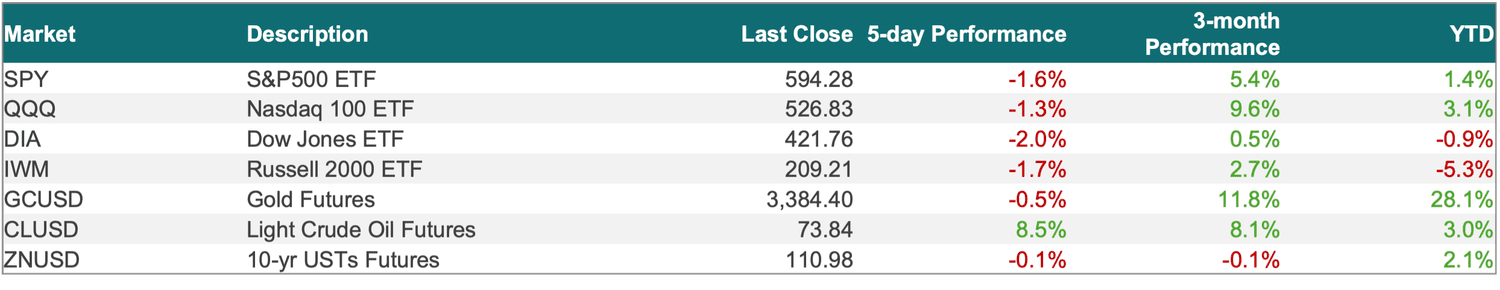
Crude Oil (CLUSC) rallied a robust +8.5%, marking one of its strongest weekly gains this year, as fears of supply disruption in the Persian Gulf collided with an unexpectedly large draw in U.S. inventories. Despite the risk-off mood in equities, Gold (GCUSD) pulled back slightly (–0.5%) but remains sharply higher on the year (+28.1% YTD), retaining its haven appeal as real yields flatten and inflation expectations remain unanchored. Bond markets saw more muted action. 10-year U.S. Treasury futures (ZNUSD) slipped just –0.1%, as Fed-related repricing and geopolitical hedging balanced out dovish macro data.
The midweek FOMC meeting delivered few surprises on the policy front but injected fresh uncertainty into the rate path. The Fed held rates steady at 4.25–4.50%, as expected, but the updated dot plot revealed a split committee: 7 of 19 officials now see no cuts in 2025, and the median projection for this year was revised to just one 25bps cut, down from two in March. Chair Powell acknowledged slowing inflation but warned against premature easing, stating the labour market still shows “remarkable strength.” The market reaction was choppy - 2Y yields dipped briefly, but risk assets sold off into the close as participants digested a more cautious path for easing. With policy becoming more data-dependent and political pressure increasing, the risk premium around forward guidance has widened materially.
The macro calendar outside the Fed provided little directional clarity. Weaker-than-expected housing starts, an underwhelming Philly Fed survey, and a soft retail sales print supported the disinflation narrative. However, Friday’s University of Michigan Consumer Sentiment print surprised sharply to the upside, registering the highest reading since early 2023. More troubling for the Fed, 1-year inflation expectations held at 5.1%, frustrating hopes of a dovish pivot. Equity bulls were further challenged by continued geopolitical escalation, with Iran threatening retaliation for recent Israeli actions. This backdrop pushed the VIX back near the 20 level and underscored growing hedging activity in options markets.
From a tactical perspective, market breadth deteriorated meaningfully. Participation in recent rallies has narrowed to fewer names, especially within tech, and momentum indicators are flashing early-stage reversal signals. Short-term volatility metrics have begun to steepen, and traders are increasingly pricing in asymmetric downside tails heading into month-end. If upcoming inflation and growth data fail to reset expectations positively, this week’s pullback may prove to be the beginning of a broader tactical pullback across risk assets.
Importantly, positioning data suggests that institutional portfolios had recently re-levered into equities, particularly in the tech and communication services sectors. With sentiment still elevated and dealer gamma flipping short, the path of least resistance could remain lower in the near term unless macro or geopolitical surprises deliver upside relief. Meanwhile, the resilience in oil and continued stickiness in inflation expectations raise the possibility that the market may soon have to grapple with a stagflation-lite regime — one that complicates the clean rate-cut narrative and demands more defensive equity leadership.
To read the full version of this week’s insights please click the “view in PDF” button at the top.
This investment thesis is prepared by Altai Capital for informational and analytical purposes. Investors should conduct independent due diligence and consult with financial advisors before making investment decisions. Past performance and historical precedents do not guarantee future results. Altai Capital’s portfolio may contain the mentioned security and thus this publication have vested interests.
This note is published for informational purposes only and is not investment advice or a recommendation to buy or sell any security. The author may hold positions in securities discussed. See the full disclaimer in the footer.
Keep reading
 Research Summit
11 October 2025 · 2 min read
$NTGR, Netgear Inc. - Likely Regulatory Tailwinds
Netgear represents a compelling opportunity to capitalize on potential U.S. regulatory action against Chinese router manufacturer TP-Link, which commands 65% of the U.S. market.
Read more Markets
7 September 2025 · 7 min read
Labour Markets Slowly Deteriorate as Inflation Buoys - week ending 07/09/2025
Equities digested a mixed macro tape but finished the week with a mild risk-on tone at the index level. SPY eked out +0.3%, while QQQ and IWM outperformed (+1.0% and +1.1%), with DIA slipping −0.2%.
Read more Markets
6 July 2025 · 8 min read
Markets at Extremes as we Enter Trade News Week - week ending 06/07/2025
U.S. equity markets extended their bullish streak through the shortened holiday week, with strong breadth and firm price action across all major indices.
Read more