Market Insights·27 April 2025·2 min read·Alexander Guselnikov
Short Covering or Structural Turn? - week ending 27/04/2025
Markets staged a powerful rebound this week, driven by a broad-based risk-on shift as investor sentiment improved.
Markets Performance
Markets staged a powerful rebound this week, driven by a broad-based risk-on shift as investor sentiment improved on the back of strong durable goods orders, resilient labour market data, and cooling inflation expectations, alongside solid mega-cap earnings beats. The S&P 500 (SPY) rallied +4.6%, the Nasdaq 100 (QQQ) outperformed with a +6.4% gain, and the Dow (DIA) rose +2.5%. Small caps (IWM) also participated, climbing +4.1%, although they remain heavily negative for the year (–12.1% YTD) and over the last three months (–15.1%).
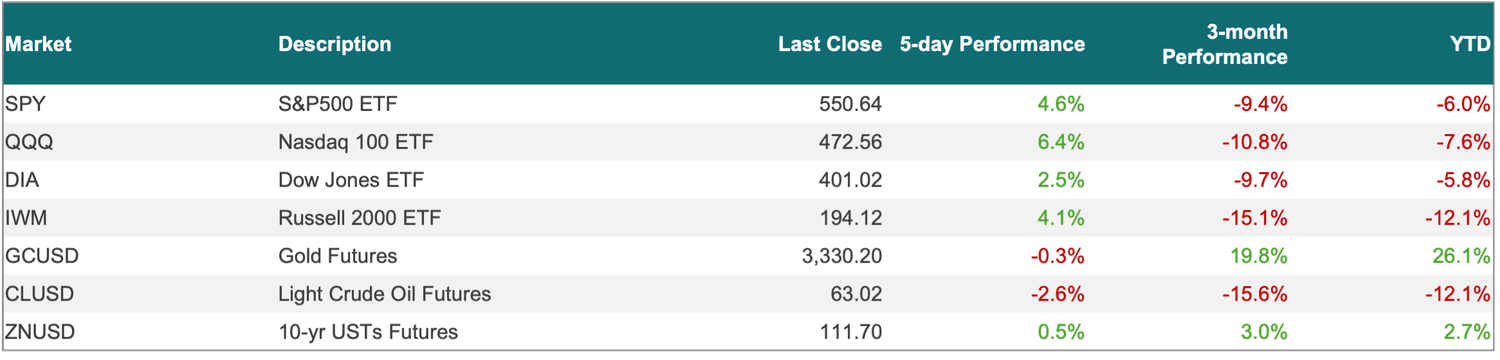
Commodities delivered a mixed signal. After months of near-relentless strength, gold futures finally reversed slightly, slipping –0.3% on the week despite still-elevated inflation risks and geopolitical uncertainty. The weakness likely reflects profit-taking flows following April’s parabolic move, alongside a broader risk-on sentiment and temporary stabilization in real yields. Oil prices continued to correct lower, falling –2.6%, as concerns over Middle East supply disruptions eased and macro growth signals moderated. 10-year Treasury futures posted a mild +0.5% gain, showing that demand for duration remains intact even as equity risk appetite recovers.
Importantly, sentiment metrics reveal an increasingly overbought market, one in which it has finally become advantageous to select individual stocks over broad markets. The percentage of S&P 500 stocks above their 5-day moving averages surged to the highest levels of 2025, while the 20-day moving average breadth also flashed preliminary overbought conditions. Such extended readings suggest the market could be vulnerable to a tactical pullback, particularly into a critical earnings stretch and key macro releases like next week’s Core PCE inflation report.
This week’s rally was fuelled by a potent mix of short-covering, bearish exhaustion, and renewed tactical optimism, with major tech earnings delivering broad upside surprises. Positive results from Alphabet, Netflix, ASML, and TSMC reinforced growth leadership, though Tesla and Intel injected a note of caution with margin compression and mixed forward commentary. Looking ahead, Microsoft, Meta, Amazon, Apple, and SoFi headline next week’s earnings slate, representing critical tests for sustaining the rally into May.
Yet, underlying fragilities remain. Credit spreads, while tightening sharply this week, are still elevated versus early-year norms. Macro headwinds — including sticky services inflation, high nominal rates, and unresolved global trade frictions — have not disappeared, though markets increasingly appear to be frontrunning bad news and leaning into a soft-landing narrative.
In short, while the rally could extend further if positive catalysts continue to materialize, near-term caution is warranted. Markets are tactically strengthening but increasingly extended, and the next leg higher will likely require confirmation from tangible improvements in earnings momentum, inflation moderation, or further trade diplomacy gains. Until then, risks of consolidation or mean reversion should not be underestimated.
To read the full version of this week’s insights please click the “view in PDF” button at the top.
This investment thesis is prepared by Altai Capital for informational and analytical purposes. Investors should conduct independent due diligence and consult with financial advisors before making investment decisions. Past performance and historical precedents do not guarantee future results. Altai Capital’s portfolio may contain the mentioned security and thus this publication have vested interests.
This note is published for informational purposes only and is not investment advice or a recommendation to buy or sell any security. The author may hold positions in securities discussed. See the full disclaimer in the footer.
Keep reading
 Research Summit
11 October 2025 · 2 min read
$NTGR, Netgear Inc. - Likely Regulatory Tailwinds
Netgear represents a compelling opportunity to capitalize on potential U.S. regulatory action against Chinese router manufacturer TP-Link, which commands 65% of the U.S. market.
Read more Markets
7 September 2025 · 7 min read
Labour Markets Slowly Deteriorate as Inflation Buoys - week ending 07/09/2025
Equities digested a mixed macro tape but finished the week with a mild risk-on tone at the index level. SPY eked out +0.3%, while QQQ and IWM outperformed (+1.0% and +1.1%), with DIA slipping −0.2%.
Read more Markets
6 July 2025 · 8 min read
Markets at Extremes as we Enter Trade News Week - week ending 06/07/2025
U.S. equity markets extended their bullish streak through the shortened holiday week, with strong breadth and firm price action across all major indices.
Read more