Market Insights·18 May 2025·3 min read·Alexander Guselnikov
Squeezed Higher, Positioned Tighter - week ending 18/05/2025
Markets extended their May rally with conviction this week, powered by a combination of tariff de-escalation, tamer inflation.
Markets Performance
Markets extended their May rally with conviction this week, powered by a combination of tariff de-escalation, tamer inflation data, and a broad-based risk-on surge centred around mega-cap technology. A 90-day mutual rollback of tariffs between the U.S. and China—larger than anticipated—acted as a potent upside catalyst, rekindling global risk appetite and lifting sentiment across asset classes. Earlier in April we called for forward news asymmetry, favouring a wave of bullish news in the proceeding weeks, which coupled with overwhelming data from the price action that formed the lows - formed a conviction long on equity markets as a whole. Aforementioned tickers like Tesla (TSLA), Tempus AI (TEM) and Take-Two Interactive (TTWO) have done exceedingly well.
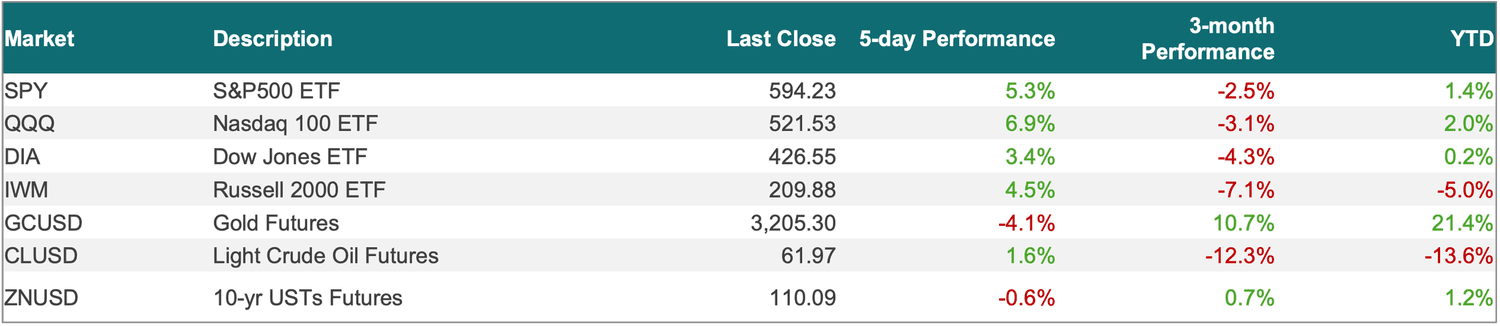
The tariff rollback was interpreted as a major step toward re-engagement between the world’s two largest economies, with the potential for follow-through if progress toward a longer-term trade resolution continues. Meanwhile, April CPI and PPI reports surprised to the downside, reinforcing the narrative that inflationary pressures—while still persistent—may be gradually normalizing. The S&P 500 (SPY) climbed +5.3% for the week, erasing all of its 2025 losses and entering positive territory YTD.
Commodities saw a stark reversal. Gold futures (GCUSD) dropped –4.1%, suffering their steepest weekly decline in over four months. The move lower came as real yields ticked up and equity markets rallied, undercutting demand for safe-haven assets. Profit-taking following gold’s parabolic rise through April also likely contributed to the unwind. Crude oil (CLUSD) advanced +1.6%, breaking a multi-week downtrend as inventories declined and supply concerns faded. The bounce, however, remains fragile, with broader demand signals mixed. In fixed income, 10-year Treasury futures (ZNUSD) declined –0.6% as yields rose modestly following Moody’s downgrade of U.S. sovereign credit to Aa1 from Aaa, citing unsustainable debt dynamics and interest payment burdens. The 10-year yield ended at 4.48%, up 3 basis points on the week, reflecting a marginal repricing of credit risk in the wake of the downgrade and a recognition of mounting fiscal constraints.
At the micro level, investor sentiment remained ebullient despite signs of fatigue. Consumer sentiment dipped to 50.8f rom 52.2 in April, while 1-year inflation expectations jumped to 7.3%, the highest reading in months. This data, derived from the University of Michigan’s preliminary May survey, underscored a subtle but important divergence: the equity market is rallying on hopes of inflation moderation, while the consumer remains burdened by cost-of-living pressures. Nonetheless, investors appeared more focused on momentum and headline catalysts than on underlying frictions.
Breadth initially broadened early in the week but narrowed by Friday, with strength increasingly concentrated in a handful of mega-cap growth names. The Vanguard Mega Cap Growth ETF (MGK) rose +7.2%, led by NVIDIA (+16%), Apple (+6.4%), and other AI-related plays.
The market narrative remains anchored in soft-landing optimism, robust liquidity, and the belief that the Fed’s tightening cycle is in its terminal phase. Importantly, downside inflation surprises are now being interpreted as confirmation that restrictive policy is working, not as a signal of economic fragility. However, with price and sentiment indicators stretched, longer term inflation expectations rising, and deficit concerns rekindled, the risk of a sharp consolidation or reversal is elevated. Next week’s Monday reaction to the Moody’s downgrade, and data including flash PMIs, Core PCE, and continued earnings from large-cap retailers, will be critical in determining how much longer this rally can last. By any technical indicator, we are now very stretched on the indexes with increasingly narrowing breadth and weakening event setups, indicating a pause in animal spirits is soon to come.
This note is published for informational purposes only and is not investment advice or a recommendation to buy or sell any security. The author may hold positions in securities discussed. See the full disclaimer in the footer.
Keep reading
 Research Summit
11 October 2025 · 2 min read
$NTGR, Netgear Inc. - Likely Regulatory Tailwinds
Netgear represents a compelling opportunity to capitalize on potential U.S. regulatory action against Chinese router manufacturer TP-Link, which commands 65% of the U.S. market.
Read more Markets
7 September 2025 · 7 min read
Labour Markets Slowly Deteriorate as Inflation Buoys - week ending 07/09/2025
Equities digested a mixed macro tape but finished the week with a mild risk-on tone at the index level. SPY eked out +0.3%, while QQQ and IWM outperformed (+1.0% and +1.1%), with DIA slipping −0.2%.
Read more Markets
6 July 2025 · 8 min read
Markets at Extremes as we Enter Trade News Week - week ending 06/07/2025
U.S. equity markets extended their bullish streak through the shortened holiday week, with strong breadth and firm price action across all major indices.
Read more