Market Insights·13 April 2025·2 min read·Alexander Guselnikov
Tariff Freezes Buoy Markets - week ending 13/04/2025
Markets delivered a powerful rebound this week, reversing a multi-week selloff as softer inflation data, a pause in tariff escalation, and deeply oversold conditions.
Markets Performance
Markets delivered a powerful rebound this week, reversing a multi-week selloff as softer inflation data, a pause in tariff escalation, and deeply oversold conditions triggered a sharp risk-on move. Equities surged midweek on the back of short covering and improved macro sentiment, with the S&P 500 ETF (SPY) rallying +5.7%, its strongest weekly performance since late 2023. The Nasdaq 100 (QQQ) led with a +7.5% gain, powered by strength in AI, semiconductors, and software. The Dow Jones (DIA) added +4.9%, while small caps (IWM) lagged, rising just +1.7% amid continued pressure on regional banks and rate-sensitive cyclicals.
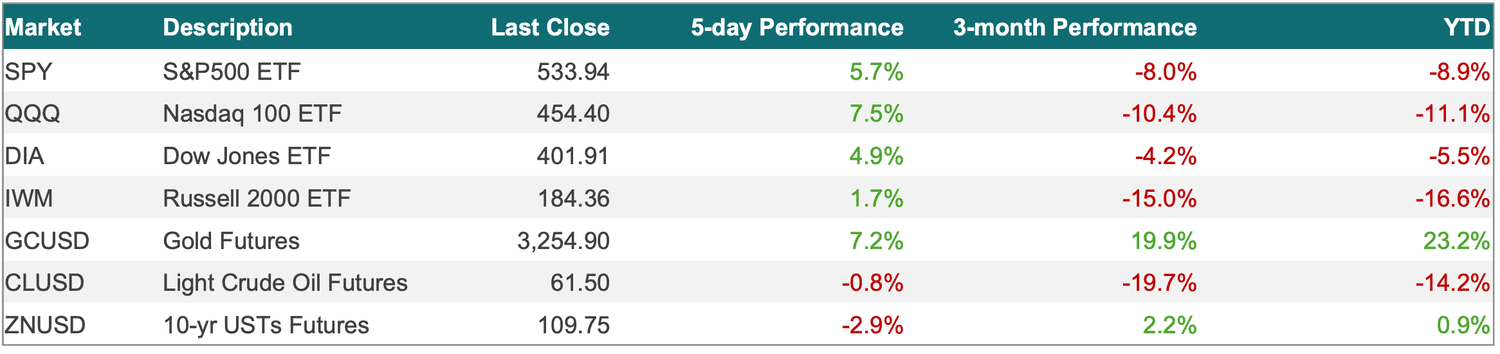
Commodity and rate markets echoed the shift in sentiment but remained bifurcated. Gold futures (GCUSD) jumped +7.2%, nearing all-time highs as investors rotated into hard assets amid rising inflation expectations and falling real yields. The move was supported by a surge in consumer inflation expectations to 6.7%, the highest since 1981. Oil (CLUSD) reversed lower by –0.8%, despite persistent geopolitical risks, as demand signals and inventory builds weighed on price action. Meanwhile, 10-year U.S. Treasury futures (ZNUSD) dropped –2.9%, reflecting higher long-end yields following the Fed’s reaffirmation of inflation vigilance and the March FOMC minutes showing reduced appetite for early rate cuts.
Breadth improved notably, though the rally remains narrow under the surface. The percentage of S&P 500 stocks trading above their 50-day moving average climbed to 35%. This confirms a technical improvement but highlights that many names remain in corrective territory, particularly across industrials and small caps.
Credit markets added a note of caution. Despite the equity surge, the ICE BofA U.S. High Yield OAS widened to 4.42%, up from 4.01% the prior week, signalling ongoing stress in lower-rated corporate debt. This divergence between equity and credit suggests that while positioning and sentiment drove equity gains, fundamental concerns around financing conditions and growth outlook remain unresolved.
This suggests the move may be more relief-driven for now, although sustained upside surprises on real inflation data and further tariff de-escalation would help bolster longer-term market sentiment and improve forward-looking indicators. As earnings season accelerates and macro headwinds persist, this rally remains fragile but tactically constructive, with much riding on whether inflation momentum and trade clarity continue to improve in the weeks ahead.
To read the full version of this week’s insights please click the “view in PDF” button at the top.
This investment thesis is prepared by Altai Capital for informational and analytical purposes. Investors should conduct independent due diligence and consult with financial advisors before making investment decisions. Past performance and historical precedents do not guarantee future results. Altai Capital’s portfolio may contain the mentioned security and thus this publication have vested interests.
This note is published for informational purposes only and is not investment advice or a recommendation to buy or sell any security. The author may hold positions in securities discussed. See the full disclaimer in the footer.
Keep reading
 Research Summit
11 October 2025 · 2 min read
$NTGR, Netgear Inc. - Likely Regulatory Tailwinds
Netgear represents a compelling opportunity to capitalize on potential U.S. regulatory action against Chinese router manufacturer TP-Link, which commands 65% of the U.S. market.
Read more Markets
7 September 2025 · 7 min read
Labour Markets Slowly Deteriorate as Inflation Buoys - week ending 07/09/2025
Equities digested a mixed macro tape but finished the week with a mild risk-on tone at the index level. SPY eked out +0.3%, while QQQ and IWM outperformed (+1.0% and +1.1%), with DIA slipping −0.2%.
Read more Markets
6 July 2025 · 8 min read
Markets at Extremes as we Enter Trade News Week - week ending 06/07/2025
U.S. equity markets extended their bullish streak through the shortened holiday week, with strong breadth and firm price action across all major indices.
Read more